Boat Insurance for Pontoon Boats
Find the Right Pontoon Boat Insurance with Roamly
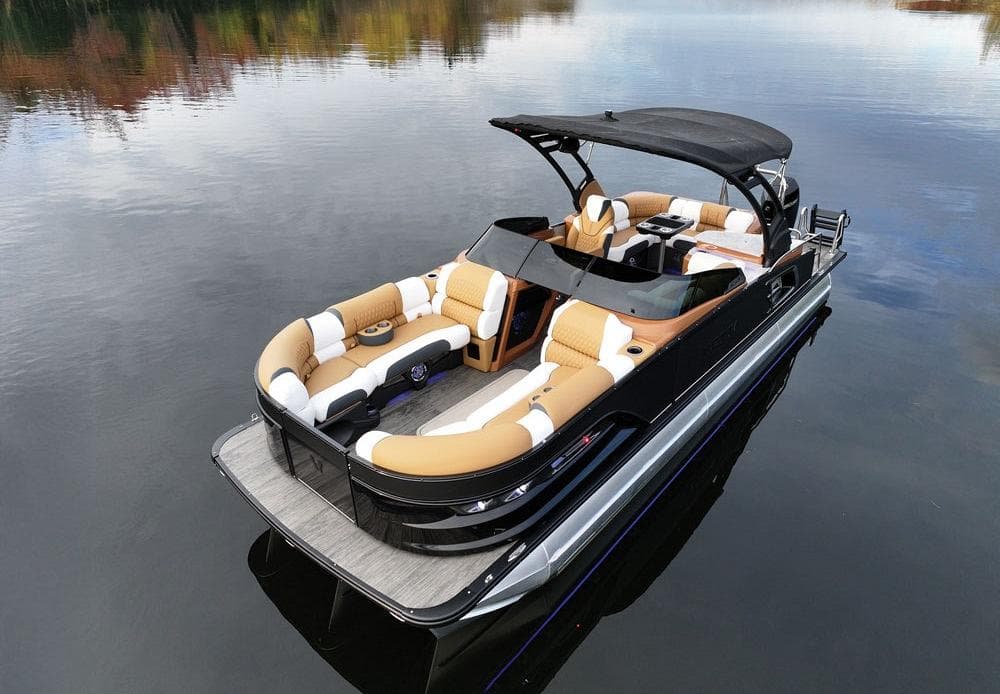
Coverage Options Built for Pontoon and Tritoon Owners, From Carriers Who Know the Water
Why Choose Roamly for Pontoon Boat Insurance?
- Multiple Carriers, One Quote: Roamly is a brokerage, so we shop a panel of marine-focused carriers instead of selling you one company's policy.
- Coverage for the Whole Crew: Carriers we work with may offer guest medical payments and liability options sized for a boat that carries a crowd.
- Agreed Value Options: Your pontoon may be insured for an amount you agree on up front, not a value that drops every season.
- Gear and Electronics Options: Coverage options may be available for the sound system, coolers, fishing gear, and water toys you bring aboard.
- Licensed Marine Specialists: Our licensed agents boat too, and they'll help you compare coverage in plain language.
At Roamly, we're not just insurance agents — we're boaters who know a pontoon is where the whole family ends up on a summer Saturday. A boat built to carry a crowd needs liability and guest coverage that keeps up, and we'll help you find a policy that fits how you actually use yours.
How Much Does Pontoon Boat Insurance Cost?
Pontoon boat insurance can be one of the more affordable types of boat coverage. As of October 2026, Progressive advertises basic liability-only pontoon coverage starting as low as about $100 a year (not available in D.C.), and published agency estimates put full coverage — liability plus damage to the boat itself — at roughly $275 to $900 or more a year. Your price depends on your pontoon's value, horsepower, and length, where you keep and use it, and your boating experience. Tritoons with bigger engines and pontoons used on coastal water can cost more to insure.
- Quotes From Multiple Carriers: Compare options side by side instead of taking one company's price.
- Personalized Quotes: Based on your boat, your waters, and how often you're out.
- Discounts You May Qualify For: Carriers we work with may offer savings for a boater safety course, off-season storage, or insuring more than one boat.
Average Cost Range (as of October 2026):
- Liability-Only Policies: From about $100 per year (Progressive's advertised starting price for basic liability; not available in D.C.).
- Full Coverage Policies: About 275–900+ per year in published agency estimates, with high-horsepower tritoons and coastal use at the higher end.
Coverage Type | Liability-Only Policy | Full Coverage Policy |
|---|---|---|
Liability for damage or injuries you cause | ✓ | ✓ |
Damage to your pontoon (collision, theft, storm) |
Key Features of Roamly's Pontoon Boat Insurance
- Physical Damage Protection: Coverage options for collision, theft, vandalism, fire, and storm damage, whether your pontoon is on the water or tied up at the dock.
- Guest Medical Coverage: Medical payments options for guests hurt aboard — worth a close look on a boat built to carry a crowd.
- Water Sports Liability: Some carriers we work with include liability for tubing, skiing, and wakeboarding behind your boat.
- Docking Mishaps: Coverage may be available for damage from bumping a dock or another boat while you're coming in.
- Flexible Deductibles: Adjust your deductible to find the balance between coverage and cost that works for you.
Ready to Protect Your Pontoon?
Get a Quote on Pontoon Boat Insurance That Fits How You Use It
Whether it's sandbar Saturdays or sunset cruises with the grandkids, Roamly works with carriers who understand pontoon life. We'll help you find coverage so you can focus on the water.
Why Roamly?
True replacement value
Your boat isn't just worth the Blue Book numbers. We'll find you a policy that insures it for what it's actually worth – including your upgraded electronics.
Real-world coverage
From shallow water prop strikes to dock collisions, we cover the stuff that actually happens to recreational boaters.
Usually not enough. Many homeowners policies cover only smaller boats with low-horsepower motors, with limits that vary by policy, often only on inland waters, and they may cap damage to the boat itself at a low limit. Many pontoons run more horsepower than that, so a separate boat policy is usually the way to get real protection. Check your homeowners policy to see what limits apply.
In most states, no law requires it, though a few states require liability coverage for certain motorized boats, and the rules vary by state. If you finance your pontoon, your lender will likely require coverage, and some marinas ask for proof of liability coverage before you can rent a slip.
Pontoons carry more people than most boats their size, so liability and guest medical coverage matter more. Tritoons with bigger engines may cost more to insure, since horsepower is a rating factor, and some carriers classify boats 27 feet and longer as yachts, which can change the policy a long tritoon lands in. Roamly can help you compare how different carriers treat your boat.
Still have questions?
Call us at 877.725.1245
Buy Insurance for a Pontoon Boat
Find the Right Pontoon Boat Insurance with Roamly
* Roamly is an insurance agency, not a carrier. Coverage, limits, and availability vary by carrier and by state, and are subject to underwriting approval.
Roamly Insurance Group, LLC ("Roamly") is a licensed general agent for affiliated and non-affiliated insurance companies. Roamly is licensed as an agency in all states in which products are offered. Roamly license numbers. Availability and qualification for coverage, terms, rates, and discounts may vary by jurisdiction. We do not in any way imply that the materials on the site or products are available in jurisdictions in which we are not licensed to do business or that we are soliciting business in any such jurisdiction. Coverage under your insurance policy is subject to the terms and conditions of that policy and is ultimately the decision of the buyer.
Policies provided by Roamly are underwritten by Spinnaker Insurance Company, Progressive Insurance Company, Liberty Mutual Insurance Company, Foremost Insurance Company, National General Insurance, and others.