Boat Insurance for Yachts & Cabin Cruisers
Find the Right Yacht and Cabin Cruiser Insurance with Roamly
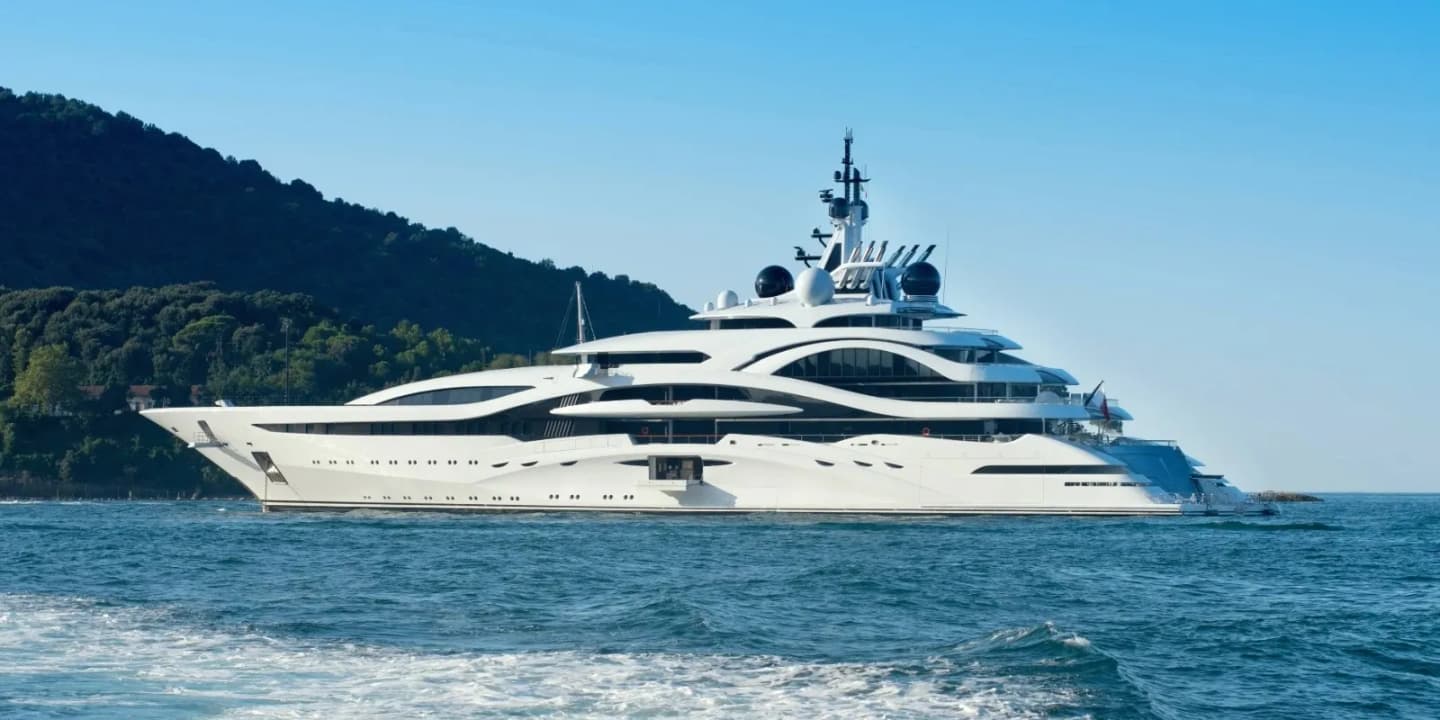
Coverage Options for Cabin Cruisers, Express Cruisers, and Yachts up to 50 Feet, From Carriers Who Know the Water
Why Choose Roamly for Yacht Insurance?
- Multiple Carriers, One Quote: For marine coverage, Roamly compares policies from a panel of marine-focused carriers, so you're not limited to one company's option.
- Agreed Value Options: Your boat may be insured for an amount you agree on up front, not a value that drops every season.
- Coverage Where You Cruise: We'll help you match your policy's navigation area to where you actually go, with extension options from some carriers for trips farther afield.
- Storm-Season Options: Carriers we work with may offer hurricane haul-out cost sharing and named-storm plans for boats kept in coastal waters.
- Licensed Marine Specialists: Our licensed agents boat too, and they'll help you compare coverage in plain language.
At Roamly, we're not just insurance agents — we're boaters who know a cabin cruiser is a weekend getaway with a helm. Between overnight guests, a home slip, storm season, and longer runs down the coast, there's more to cover than on a day boat. We work with carriers that insure boats valued up to $500,000 and up to 50 feet long, and we'll help you find a policy that fits how you cruise.
How Much Does Yacht Insurance Cost?
Yacht and cabin cruiser insurance is usually priced as a share of what the boat is worth. As of October 2026, published industry estimates commonly put yacht insurance at about 1% to 2% of the boat's insured value per year, and some estimates run as high as 5% for boats kept in hurricane-prone waters. For comparison, Progressive's data for its one-watercraft boat policies puts average premiums at about $274 a year in Wisconsin to about $868 in Florida. Your price depends on your boat's value, length, and age, where you keep it, your navigation area, and your boating experience.
- Quotes From Multiple Carriers: Compare options side by side instead of taking one company's price.
- Personalized Quotes: Based on your boat, your home port, and your cruising plans.
- Discounts You May Qualify For: Carriers we work with may offer savings for a boater safety course, a lay-up period, or a documented hurricane plan.
Average Cost Range (as of October 2026):
- General Boat Averages: About 274–868 per year, depending on the state, in Progressive's data for its one-watercraft boat policies.
- Cabin Cruisers and Yachts: Commonly about 1%–2% of insured value per year, or roughly 2,500–5,000 a year on a $250,000 boat.
- Hurricane-Prone Waters: Some published estimates run as high as 5% of insured value per year.
Coverage Type | Liability-Only Policy | Full Coverage Policy |
|---|---|---|
Liability for damage or injuries you cause | ✓ | ✓ |
Damage to your boat (collision, sinking, storm, lightning) | Not included | ✓ |
Hurricane haul-out cost sharing | Not included | Varies by carrier |
Navigation area extensions | Not included | Optional |
Agreed value | Not included | Optional |
Personal effects | Not included | Optional |
Features to Look for When Shopping for Yacht Coverage with Roamly
- Physical Damage Coverage: Look for protection against collision, grounding, fire, theft, lightning, storm damage, and sinking, whether you're underway or in your slip.
- Hurricane Haul-Out Cost Sharing: If you keep your boat in coastal waters, ask whether the policy shares the cost of hauling out or securing it ahead of a named storm.
- Navigation Area: Make sure the policy's navigation area matches your cruising grounds, and ask about extensions for trips to places like the Bahamas.
- Liability and Guest Medical Payments: Make sure your liability and medical payments limits fit the guests who spend the day, or the weekend, aboard.
- Deductible Choices: Yacht deductibles are often set as a percentage of insured value, so compare options to find the balance between coverage and cost that works for you.
Ready to Protect Your Cruiser?
Get a Quote on Yacht Insurance That Fits How You Cruise
Whether it's a weekend at the sandbar, a raft-up with friends, or a run down the coast, Roamly works with carriers who understand cabin cruisers and yachts. We'll help you find coverage so you can focus on the trip.
Why Roamly?
True replacement value
Your boat isn't just worth the Blue Book numbers. We'll find you a policy that insures it for what it's actually worth – including your upgraded electronics.
Real-world coverage
From shallow water prop strikes to dock collisions, we cover the stuff that actually happens to recreational boaters.
Insurance by boaters, for boaters
Our marine specialists actually spend their weekends on the water. They speak your language because they boat too.
There's no single cutoff. Many carriers start writing yacht policies at around 26 or 27 feet, though some draw the line elsewhere, and many cuddy cabins under that length are insured as regular boats. Roamly works with carriers that insure boats valued up to $500,000 and up to 50 feet long.
It depends on the carrier. Some carriers don't require a survey to buy a policy, while others may ask for one on used boats past a certain age or value. Thresholds vary by carrier. If you're buying a used cruiser, a pre-purchase survey can also help document the boat's condition and value for an agreed value policy.
Storm damage is generally covered under physical damage coverage, but boats in hurricane-prone areas often carry a separate named-storm deductible, which some published sources say can reach 10% of the boat's value. Some carriers ask for a hurricane plan, some offer haul-out cost sharing, and some restrict or exclude coverage in certain hurricane-prone areas.
It depends on the carrier. Some carriers exclude boats used as a primary residence, while others may cover a liveaboard if you disclose it up front. Marinas may also set their own insurance requirements for liveaboard tenants, so tell your agent how you use the boat before you buy a policy.
The biggest factors are your boat's value, length, age, and hull material, where you keep it and whether that's in a hurricane zone, how far you cruise, whether you choose agreed value or actual cash value, your boating experience and claims history, and your deductible. A lay-up period, a boater safety course, or a documented hurricane plan may also earn a discount with some carriers.
Many policies exclude wear and tear, gradual deterioration, and damage from marine life, mold, animals, or insects, and some exclude manufacturer or design defects. Freezing damage may also be excluded if the boat wasn't winterized as the policy requires, mechanical breakdown, where it's offered, is typically an optional add-on, and cruising outside your navigation area without approval can leave you without coverage. Roamly can help you compare optional coverages, like mechanical breakdown, that may fill some of these gaps.
Still have questions?
Call us at 877.725.1245
Buy Insurance for a Yacht or Cabin Cruiser
Find the Right Yacht and Cabin Cruiser Insurance with Roamly
* Roamly is an insurance agency, not a carrier. Coverage, limits, and availability vary by carrier and by state, and are subject to underwriting approval.
Roamly Insurance Group, LLC ("Roamly") is a licensed general agent for affiliated and non-affiliated insurance companies. Roamly is licensed as an agency in all states in which products are offered. Roamly license numbers. Availability and qualification for coverage, terms, rates, and discounts may vary by jurisdiction. We do not in any way imply that the materials on the site or products are available in jurisdictions in which we are not licensed to do business or that we are soliciting business in any such jurisdiction. Coverage under your insurance policy is subject to the terms and conditions of that policy and is ultimately the decision of the buyer.
Policies provided by Roamly are underwritten by Spinnaker Insurance Company, Progressive Insurance Company, Liberty Mutual Insurance Company, Foremost Insurance Company, National General Insurance, and others.
© 2026 Roamly All rights reserved.