Boat Insurance for Alaska
Alaska boat insurance for boaters who know the water.
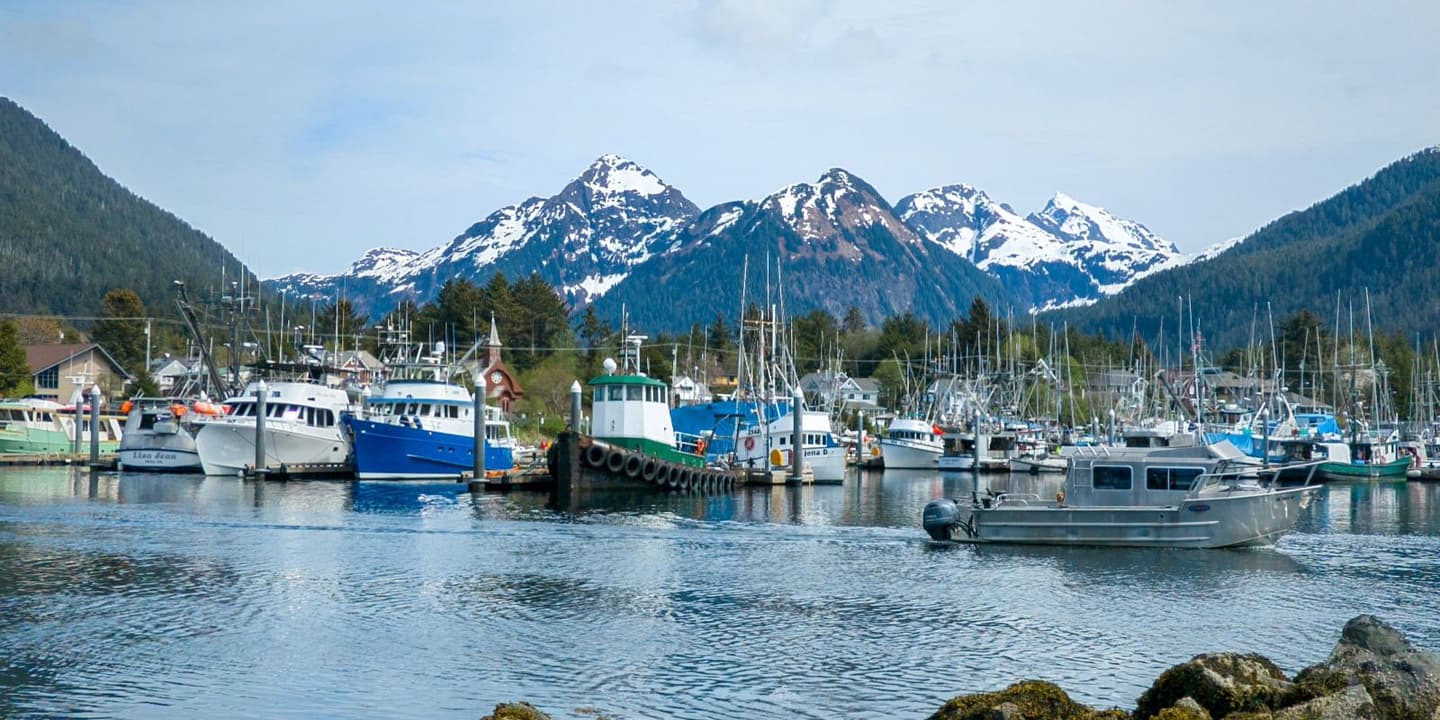
From the Kenai River and Kachemak Bay to Resurrection Bay and Prince William Sound, Roamly works with carriers who understand how Alaskans actually boat.
Alaska at a Glance
Requirement | Details |
|---|---|
Insurance requirement | Not required by state law for private recreational boats. Owners can be held liable when someone using the boat with permission operates it negligently, and lenders and harbors often require coverage. |
Boater education | No boater education requirement and no statewide minimum operating age. The Alaska Office of Boating Safety offers a free, NASBLA-approved Alaska Water Wise course. |
Boating under the influence | Alaska's DUI law covers boats (0.08 BAC). A first offense means at least 72 consecutive hours in jail and a minimum $1,500 fine, and the court can order your boat forfeited. |
Registration | Motorboats used principally in Alaska register with the Division of Motor Vehicles. As of October 2026, registration is $24 for three years regardless of length, and boats over 24 feet must be titled unless documented with the Coast Guard. |
Requirements and regulations may change. Verify with the Alaska Division of Insurance and the Alaska Office of Boating Safety for the most current information.
What you need to know about Boat Insurance in Alaska
Alaska doesn't require boat insurance, but it holds owners liable for negligent operation of their boats, treats boating under the influence as a criminal DUI with mandatory jail time and fines, and requires an accident report for damage over just $500. Here's what actually shapes your policy.
Alaska's Boat Insurance Rules
No Alaska law requires insurance on a private recreational boat or personal watercraft. You can still be held responsible for damage or injuries you cause on the water, and marinas and lenders set their own coverage rules. Alaska also makes the owner liable when someone using the boat with permission operates it negligently. We'll help you figure out what makes sense for how you boat.
Agreed Value for Your Boat
Your aluminum landing craft with a repower, a new cabin heater, and upgraded electronics isn't a stock boat. Roamly works with carriers who may value the work you've put in, not some database guess.
Electronics and Gear Coverage
Radar, chartplotters, VHF radios, rods, and halibut gear add up fast. Roamly works with carriers who may offer coverage options for marine electronics and the personal gear you bring aboard.
Coverage Lenders and Marinas Ask For
If you finance your boat, your lender will likely require coverage for the boat itself, and many marinas ask for proof of liability coverage before you can rent a slip or store your boat for the winter. Roamly works with carriers who may help you meet those requirements, and we'll help you get the paperwork in order.
Protection Beyond Basics
Type | Details |
|---|---|
Mechanical Breakdown Coverage | Engines fail at the worst times — like far out in Prince William Sound, where help can be hours away. Through Roamly's carrier partners, coverage may be available to help with sudden mechanical breakdowns beyond warranty. |
Guest Medical Coverage | Summer salmon trips on the Kenai River mean friends and family aboard, wet decks, and lines in the water. Roamly works with carriers who may offer medical payments options for guests hurt on your boat. |
Docking Mishaps | Big tides and crowded small-boat harbors lead to bumps and scrapes. Through Roamly's carrier partners, coverage may be available for damage from docking mishaps. |
Protect the Gear You Bring Aboard
A day on Resurrection Bay or a trip down the Kenai River means a lot of gear on board — rods and reels, nets, coolers, survival gear, and electronics at the helm. Many basic policies limit coverage for personal property, so check yours before your next trip. Roamly works with carriers who may offer coverage options for marine electronics and personal effects like fishing and water sports equipment, which may help you replace what's lost or damaged.
What Alaska Actually Requires
Alaska doesn't require insurance on a private recreational boat. What the state does require: registration with the Division of Motor Vehicles for every motorboat used principally in Alaska; a title for undocumented boats over 24 feet; and a life jacket on every child under 13 in an open boat or on deck. Accidents involving a death, an injury, or more than $500 in property damage must be reported to the Department of Public Safety within 20 days, and the Office of Boating Safety asks for reports within 48 hours for death or injury cases and within 10 days for others. Going without coverage may be legal, but one collision can mean damage to another boat, a dock, or someone you hurt — and liability alone doesn't pay to fix or replace your own boat. We'll help you figure out what makes sense for your situation.
Real Value for Upgraded Boats
You set up your boat the way you wanted it: a repower, a new cabin heater, upgraded electronics, and a better trailer. Book value doesn't account for the upgrades you've added. Roamly works with carriers who offer Agreed Value coverage options — we'll help document your boat so it may be insured for an agreed amount that reflects your upgrades, which may help if you ever need to file a claim.
LEGAL DISCLAIMERS
Roamly is a licensed insurance agency. Insurance policies referenced are offered through Roamly and underwritten by third-party carriers including Progressive, National General, Foremost, Liberty Mutual, American Modern, Ahoy Insurance, and Spinnaker Insurance Company, among others. Not all products or coverages are available in every state. Coverage terms, conditions, limits, deductibles, exclusions, and availability vary by state, carrier, and policy. This page is provided for general information and is not a contract of insurance. See the actual policy for a full description of coverages, terms, and conditions. Alaska law references current as of October 2026 — confirm current requirements with the Alaska Division of Insurance, the Alaska Office of Boating Safety, and the Alaska Division of Motor Vehicles.
Why Roamly?
True replacement value
Your boat isn't just worth the Blue Book numbers. We'll find you a policy that insures it for what it's actually worth – including your upgraded electronics.
Real-world coverage
From shallow water prop strikes to dock collisions, we cover the stuff that actually happens to recreational boaters.
Insurance by boaters, for boaters
Our marine specialists actually spend their weekends on the water. They speak your language because they boat too.
No. Alaska law doesn't require insurance on a private recreational boat or personal watercraft. If you finance your boat or keep it at a marina, your lender or marina will likely require coverage. Even without a mandate, you can be held responsible for damage or injuries you cause on the water. Requirements may change — verify with the Alaska Division of Insurance.
No. Alaska doesn't require boater education and has no statewide minimum age to operate a motorboat or PWC. The Alaska Office of Boating Safety offers Alaska Water Wise, a free eight-hour course approved by NASBLA and recognized by the U.S. Coast Guard, and finishing one can help if you boat in a state that requires a card.
It depends on your boat's type, size, value, and horsepower, where you keep and use it, your boating experience, and the coverage you pick. Whether you keep it in a harbor slip or on a trailer, how you store it over the winter, and adding physical damage coverage or coverage for electronics and gear will change the price. Get a personalized quote to find out your rate.
Roamly is a brokerage — we work with carriers who may offer coverage options for marine electronics like radar and chartplotters, plus personal effects like fishing gear and water sports equipment. Limits and eligibility depend on the carrier, so it's worth asking before you buy. Coverage terms, conditions, and availability vary by state and policy.
Roamly works with carriers who offer Agreed Value coverage options. We may help document your boat and its upgrades up front so it can be insured for an agreed amount, not a depreciated book value. If it's totaled, the agreed value — less any deductible — is what the policy is built around. Coverage terms, conditions, and availability vary by state and policy.
Alaska doesn't require either one. Liability pays for damage you cause to other people and their property — another boat, a dock, or someone hurt in a collision. "Full coverage" usually means adding physical damage coverage, which helps pay to repair or replace your own boat after a collision, theft, vandalism, or storm damage. If you're financing, your lender will likely require it.
Alaska's DUI law covers watercraft, so operating a boat at 0.08 BAC or higher, or while impaired, is a class A misdemeanor. A first offense brings at least 72 consecutive hours in jail and a minimum $1,500 fine, and the court can order the boat forfeited. Alaska's mandatory driver's license revocation for DUI doesn't apply when the offense happened in a watercraft. Refusing a chemical test is a separate crime with the same minimum penalties. If a violation is on your record, Roamly works with carriers that may still be able to help you find coverage. Coverage terms, conditions, and availability vary by state and policy.
It can. Alaska's credit law expressly covers personal boat and watercraft policies: insurers can use credit only alongside other substantive underwriting factors, must tell you when they use it, and must consider exceptions for extraordinary life circumstances. Your boating experience, your boat, and where you keep it are also major rating factors, and how much each one counts varies by carrier.
On most of the Kenai River Special Management Area, boats can't run outboards totaling more than 50 horsepower, and motors must be four-stroke or direct fuel-injected two-stroke engines. The 50 hp cap doesn't apply on Kenai Lake, Skilak Lake, or one upper river segment, so check Alaska State Parks rules for the stretch you plan to fish.
Still have questions?
Call us at 877.725.1245
Alaska Boat Insurance Quotes in Minutes
Alaska boat insurance for boaters who know the water.
* Roamly is an insurance agency, not a carrier. Coverage, limits, and availability vary by carrier and by state, and are subject to underwriting approval.
Roamly Insurance Group, LLC ("Roamly") is a licensed general agent for affiliated and non-affiliated insurance companies. Roamly is licensed as an agency in all states in which products are offered. Roamly license numbers. Availability and qualification for coverage, terms, rates, and discounts may vary by jurisdiction. We do not in any way imply that the materials on the site or products are available in jurisdictions in which we are not licensed to do business or that we are soliciting business in any such jurisdiction. Coverage under your insurance policy is subject to the terms and conditions of that policy and is ultimately the decision of the buyer.
Policies provided by Roamly are underwritten by Spinnaker Insurance Company, Progressive Insurance Company, Liberty Mutual Insurance Company, Foremost Insurance Company, National General Insurance, and others.
© 2026 Roamly All rights reserved.