Motorcycle Insurance for Washington
Washington motorcycle insurance for riders who know the roads.
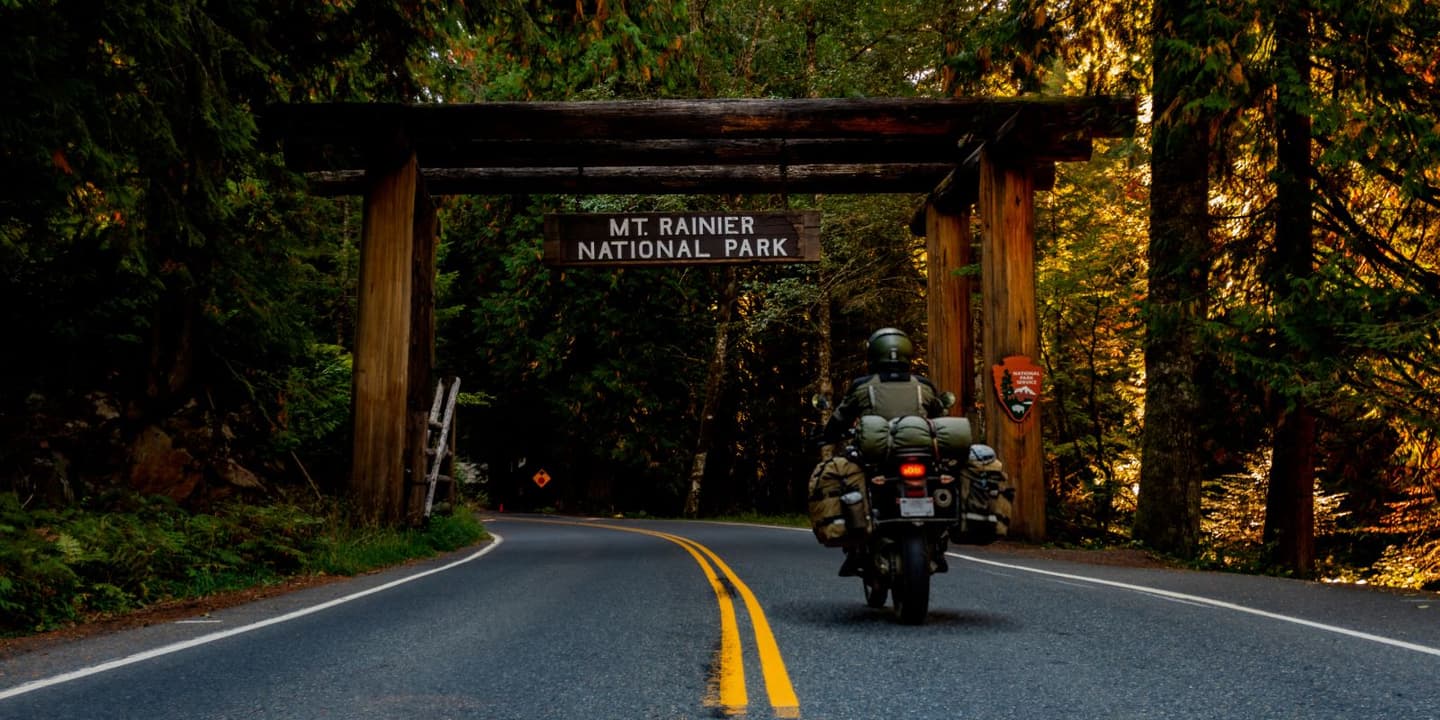
From Chuckanut Drive to the North Cascades Highway, Roamly works with carriers who understand how Washingtonians actually ride.
Washington at a Glance
Requirement | Details |
|---|---|
Minimum liability | 25/50/10 ($25k bodily injury per person, $50k per accident, $10k property damage). Insurers that write motorcycle coverage must give you information about underinsured motorist coverage and a chance to reject it in writing. |
Helmet law | Required for every rider and passenger, at every age. Operators also need glasses, goggles, or a face shield unless the bike has a windshield. |
Lane splitting | Illegal. RCW 46.61.608 bars riding between lanes or rows of vehicles, and recent bills to allow filtering or shoulder riding haven't passed the Legislature. |
Insurance mandate | Motorcycles were exempt from Washington's mandatory insurance law until July 28, 2019. Now motorcycle riders need liability coverage and proof of it (mopeds and motor-driven cycles are still exempt). |
Requirements and regulations may change. Verify with the Washington State Office of the Insurance Commissioner and the Washington State Department of Licensing for the most current information.
What you need to know about Motorcycle Insurance in Washington
Washington only started requiring motorcycle liability coverage in 2019, and the rules around injury coverage for riders work differently than they do for cars. Here's what actually shapes your policy.
Washington's 25/50/10 Minimum
The state requires $25k/$50k bodily injury and $10k property damage. Here's the detail riders miss: PIP that comes with a car policy isn't required on a motorcycle policy, and the underinsured motorist coverage on your car may not follow you onto your bike. We'll help you figure out what makes sense for how you ride. Requirements vary by state — check the Washington State Office of the Insurance Commissioner for current minimums.
Agreed Value for Custom Builds
Your Scrambler with the tracker conversion and custom tank isn't a stock bike. Roamly works with carriers who may value your sweat equity, not some database guess.
Peer-to-Peer Rental Coverage
Want to list your bike on Twisted Road or Riders Share during the dry stretches when you're not riding it? Many personal policies exclude rental use, so check yours first. Roamly works with carriers who may be able to help.
SR-22 Filing When Needed
If the Washington State Department of Licensing requires an SR-22 after a suspension, you'll need a carrier to file it and keep it active for as long as your notice says. Roamly works with carriers that file SR-22s, and we'll help you get the filing started. No judgment.
Protection Beyond Basics
Type | Details |
|---|---|
Mechanical Breakdown Coverage | Engines fail at the worst times — like halfway up to Washington Pass. Through Roamly's carrier partners, coverage may be available to help with sudden mechanical breakdowns beyond warranty. |
Riding Gear Coverage | Helmets, jackets, boots, and gloves — and in Washington, the rain gear gets as much use as the helmet. Roamly works with carriers who may offer coverage options to help protect your riding equipment. |
Agreed Value for Custom Builds | Your garage-built bike is worth more than a database number. Roamly works with carriers who offer Agreed Value coverage that may insure your build for what it's actually worth. |
Rent Your Bike Without Losing Coverage
Washington riders know the drill: some weeks, the bike stays under a cover while the rain does its thing. Listing it on Twisted Road or Riders Share during the dry stretches can help it earn its keep, but many personal policies exclude rental use — check yours before you hand over the keys. Roamly works with carriers who may cover your bike even when it's rented through legitimate platforms, which may help you earn from your bike while keeping it protected.
What Washington Actually Requires
Washington mandates 25/50/10 liability coverage for motorcycles — and has since July 28, 2019. That's $25k per person and $50k per accident for bodily injury, plus $10k for property damage, with proof of coverage on you when you ride. Your insurer has to give you information on underinsured motorist coverage for the bike and a chance to turn it down in writing — think hard before you do, since the UIM on a car policy may not cover you while you're riding. Add a helmet for you and your passenger every time, plus eye protection unless you've got a windshield. We'll help you figure out what makes sense for your situation.
Custom Builds Get Real Value
You built your bike the way you wanted it: tracker bars, Vance & Hines exhaust, custom paint, and upgraded suspension. Stock book value doesn't account for the work you put in or the parts you upgraded. Roamly works with carriers who offer Agreed Value coverage options — we'll help document your build so it may be insured for an agreed amount that reflects your upgrades, which may help if you ever need to file a claim.
LEGAL DISCLAIMERS
Roamly is a licensed insurance agency. Insurance policies referenced are offered through Roamly and underwritten by third-party carriers including Progressive, National General, Foremost, Safeco, Nationwide, Dairyland, Mercury, and Plymouth Rock, among others. Not all products or coverages are available in every state. Coverage terms, conditions, limits, deductibles, exclusions, and availability vary by state, carrier, and policy. This page is provided for general information and is not a contract of insurance. See the actual policy for a full description of coverages, terms, and conditions. Washington law references current as of September 2026 — confirm current requirements with the Washington State Office of the Insurance Commissioner and the Washington State Department of Licensing.
Why Roamly?
Tailored coverage
We know a cruiser isn't a sport bike. Roamly helps you find the coverage that fits with how you ride, from dirt trails to open roads.
Custom parts protection
Most insurers offer minimal coverage for custom parts. Our partners provide up to $20,000 in coverage for your aftermarket mods and custom work.
Track day coverage
Most insurers don’t cover organized track events, riding schools, and time trials. Push your limits. We’ll make sure you’re covered.
Washington requires 25/50/10 liability coverage: $25,000 per person and $50,000 per accident for bodily injury, plus $10,000 for property damage. Motorcycles have had to carry it since July 28, 2019. Insurers that write motorcycle policies must also give you a chance to accept or reject underinsured motorist coverage in writing. These minimums keep you legal, but they might not be enough if you cause serious damage or injury. Requirements may change — verify with the Washington State Office of the Insurance Commissioner.
Yes. Washington has a universal helmet law — every rider and passenger, every age. If your bike doesn't have a windshield, the operator also needs glasses, goggles, or a face shield.
It depends on your bike, riding history, where you live and park, and the coverage you pick. Adding underinsured motorist or medical coverage raises the price but can matter a lot for a rider. A personalized quote takes a few minutes and gives you the real number.
Roamly is a brokerage — we work with carriers who may cover your motorcycle while it's rented through platforms like Twisted Road and Riders Share. Many personal policies exclude rental use, so it's worth checking yours before you list. Coverage terms, conditions, and availability vary by state and policy.
Roamly works with carriers who offer Agreed Value coverage options. We may help document your mods up front so your bike can be insured for an agreed amount, not a depreciated database number. If it's totaled, the agreed value — less any deductible — is what the policy is built around. Coverage terms, conditions, and availability vary by state and policy.
Liability is what Washington requires — it pays for damage you cause to other people and their property. "Full coverage" usually means adding collision and comprehensive, which help pay to repair or replace your own bike after a crash, theft, vandalism, or weather damage. If you're financing, your lender will likely require both.
If the Washington State Department of Licensing requires an SR-22, it's a certificate your insurer files to prove you carry at least the minimum coverage, and it has to stay active for the period in your notice. Roamly works with carriers that file SR-22s and can help you keep it in place. Coverage terms, conditions, and availability vary by state and policy.
It can. Washington's Insurance Commissioner tried to ban credit-based rating, but a court struck the rule down in 2022, so insurers may still use credit information. Your riding record, bike, and location are also major rating factors, and how much each one counts varies by carrier.
Often not. Washington's rule that insurers offer PIP applies to car policies, not motorcycle policies, and the underinsured motorist law carves out injuries suffered while riding a motorcycle. That's why the medical and underinsured motorist options on your bike policy are worth a close look. We can help you compare them.
Still have questions?
Call us at 877.725.1245
Washington Motorcycle Insurance Quotes in Minutes
Washington motorcycle insurance for riders who know the roads.
* Roamly is an insurance agency, not a carrier. Coverage, limits, and availability vary by carrier and by state, and are subject to underwriting approval.
Roamly Insurance Group, LLC ("Roamly") is a licensed general agent for affiliated and non-affiliated insurance companies. Roamly is licensed as an agency in all states in which products are offered. Roamly license numbers. Availability and qualification for coverage, terms, rates, and discounts may vary by jurisdiction. We do not in any way imply that the materials on the site or products are available in jurisdictions in which we are not licensed to do business or that we are soliciting business in any such jurisdiction. Coverage under your insurance policy is subject to the terms and conditions of that policy and is ultimately the decision of the buyer.
Policies provided by Roamly are underwritten by Spinnaker Insurance Company, Progressive Insurance Company, Liberty Mutual Insurance Company, Foremost Insurance Company, National General Insurance, and others.
© 2026 Roamly All rights reserved.